Share
Saudi Arabia’s Printed Electronics Market: Demand Drivers and Entry Risks
The Saudi Arabia printed electronics market is gaining attention as smart packaging, flexible displays, connected devices, and energy-efficient components create new opportunities across consumer electronics and commercial applications. For companies assessing the market, the opportunity is real, but it is not a simple extension of conventional electronics sales. Demand is shaped by local procurement practices, regulatory expectations, partnership structures, climate conditions, and the ability to convert a technical concept into a reliable operating solution.
Printed electronics in Saudi Arabia should therefore be viewed less as a standalone product category and more as an enabling technology. Conductive inks, printed sensors, flexible circuits, RFID and NFC tags, electroluminescent layers, and printed battery-related components can support wider priorities in retail digitisation, logistics visibility, healthcare monitoring, smart buildings, consumer devices, and industrial automation. The commercial question is not whether the technology is innovative. It is whether it solves a local operational problem at a cost, scale, and reliability level that buyers can defend internally.
A market with visible demand signals but limited standalone measurement
Saudi Arabia has a strong case for increased adoption of connected and digitised products. Investment linked to Vision 2030 continues to support economic diversification, digital infrastructure, tourism, logistics, urban development, healthcare capacity, and manufacturing localisation. These programmes do not necessarily create direct demand for printed electronics materials. They do, however, create conditions in which sensing, identification, traceability, lightweight interfaces, and low-power connectivity become more valuable.
One difficulty in evaluating the Saudi Arabia printed electronics market is that public market statistics rarely separate it cleanly from electronics manufacturing, packaging, Internet of Things deployments, RFID systems, smart labels, display technologies, or industrial automation. Suppliers should be cautious about treating broad regional forecasts as evidence of immediate local purchasing volume. Many market reports combine the Gulf region, include conventional flexible electronics, or project long-term adoption without identifying who will fund production tooling, certification, field testing, and replacement costs.
The more useful approach is to track demand through end-use programmes. A printed sensor supplier may find its first viable opportunity through temperature-sensitive pharmaceutical packaging, not consumer electronics. A manufacturer of printed antennas may gain traction through asset tracking or smart access cards before entering mobile-device applications. Flexible display components may be relevant to retail fixtures, event systems, or specialist equipment long before they achieve mainstream household-electronics penetration.
In other words, the market is likely to develop through applications with a defined business case rather than through broad technology enthusiasm.
Where demand is most likely to emerge
Consumer electronics remains an important reference sector because Saudi consumers are digitally connected, brand-aware, and accustomed to frequent device upgrades. Yet the largest near-term openings for printed electronics may sit around consumer products rather than inside mass-market devices themselves. Global handset, television, appliance, and wearable brands generally operate through established component ecosystems and highly qualified supply chains. Entering those supply chains requires scale, quality consistency, intellectual-property protection, and a proven manufacturing record that few new market entrants can establish quickly.
More accessible opportunities are likely to appear in the surrounding commercial infrastructure.
Smart packaging and authentication
Retail, food distribution, pharmaceuticals, cosmetics, and premium consumer goods all face pressure to improve product visibility and reduce counterfeit exposure. RFID, NFC-enabled labels, printed indicators, and low-cost sensing layers can support inventory accuracy, consumer engagement, product verification, and condition monitoring. In Saudi Arabia, such solutions may be particularly relevant where products travel long distances through hot environments, are distributed through multiple channels, or require more reliable handling records.
The value proposition must be specific. A smart label that only adds a digital experience is often treated as a marketing expense. A label that reduces stock loss, improves expiry management, supports recall procedures, confirms cold-chain compliance, or enables anti-counterfeit verification can be justified through operating savings and risk reduction. Suppliers need to quantify that difference with local pilot data rather than relying on global retail examples.
Logistics, warehouses, and asset management
Saudi Arabia’s role as a regional trade and logistics hub is expanding, while large distribution centres, industrial zones, and e-commerce operations require more dependable item and asset visibility. Printed RFID antennas, low-cost sensing tags, and flexible identifiers can be relevant where the alternative is manual scanning, expensive reusable hardware, or poor inventory traceability.
However, low unit cost alone does not guarantee adoption. Warehouse operators will test read accuracy around metal racks, liquids, stacked cartons, vehicle movement, electromagnetic interference, and high ambient temperatures. A tag designed for a standard European warehouse may not perform consistently in a Saudi logistics facility without changes to antenna design, adhesive selection, substrate material, or reader placement. The commercial pilot must include these conditions; laboratory results are not enough.
Smart buildings and large development projects
New commercial districts, hospitality assets, entertainment venues, and mixed-use developments are increasing the demand for energy management, occupancy monitoring, indoor wayfinding, asset maintenance, and connected safety systems. Printed pressure sensors, touch interfaces, thin-film lighting elements, flexible control surfaces, and low-power monitoring components can be relevant in these environments.
Nevertheless, project-led demand has a characteristic risk: specification interest may be high during design, then disappear during value engineering or procurement consolidation. Technology suppliers often engage too early with architects or innovation teams but do not secure acceptance from the contractor, systems integrator, facilities operator, or budget owner. The party that appreciates the technology is not always the party that will purchase, install, and maintain it.
Healthcare and regulated monitoring applications
Wearable patches, disposable biosensors, smart medical packaging, and patient-monitoring interfaces are among the most discussed printed-electronics applications globally. Saudi Arabia’s healthcare investment and interest in digital health make the sector strategically attractive. It is also one of the slowest areas in which to assume easy commercial entry.
A solution used for diagnosis, treatment support, patient monitoring, or clinical decision-making may fall under medical-device requirements and require a level of evidence, registration, quality-system documentation, and local regulatory planning that differs sharply from a general wellness or logistics product. A printed sensor’s novelty does not reduce these obligations. Suppliers should establish the intended use, data flow, clinical claim, and responsible local entity before treating a healthcare pilot as a scalable sales route.
Climate resilience is a commercial requirement, not an engineering footnote
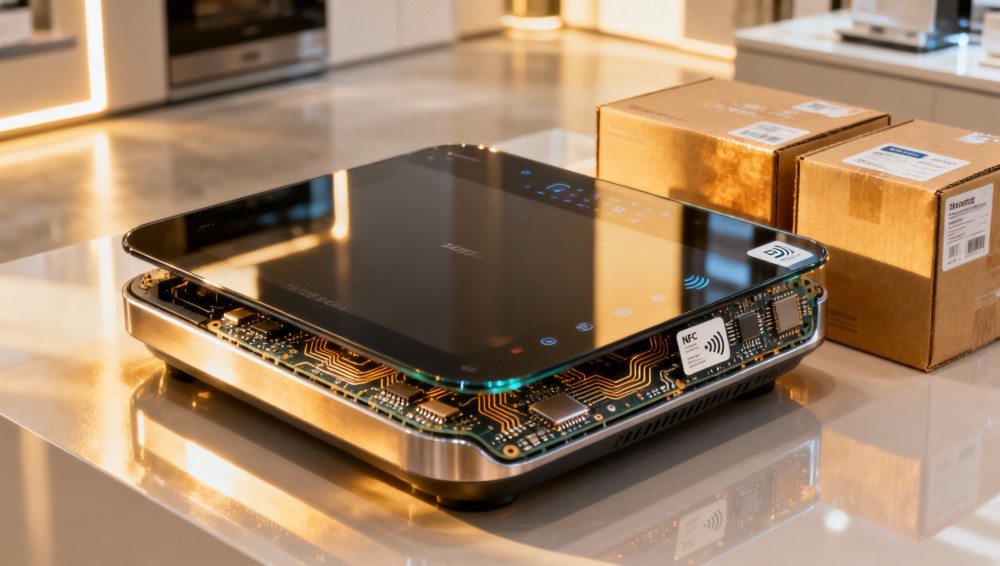
Saudi operating conditions create a major distinction between a promising prototype and a deployable product. High heat, ultraviolet exposure, dust, humidity variation near coastal areas, and demanding transport conditions can affect inks, adhesives, encapsulation layers, batteries, conductive tracks, printed antennas, and optical materials. Even products used indoors may spend substantial time in non-climate-controlled storage or transport.
For printed electronics, degradation can be subtle. Adhesion may weaken, resistance can drift, a conductive trace can crack after flexing, adhesive performance can change, display contrast can decline, or sensor calibration can move outside the useful range. A unit may still appear functional while failing the accuracy or reading-distance requirements on which the buyer’s business case depends.
This makes environmental qualification central to market entry. Suppliers should be able to explain the operating and storage limits of each layer in the finished assembly, not simply the capability of the printed component. They should also distinguish between short exposure testing and expected field life. A label intended for a two-week logistics cycle has very different validation needs from an embedded building interface expected to operate for five years.
Procurement logic favours evidence, integration capability, and local accountability
Buyers in Saudi Arabia do not purchase emerging technologies in a vacuum. They evaluate suppliers against familiar concerns: continuity of supply, warranty responsibility, local support, technical documentation, installation capability, cybersecurity exposure where applicable, and the ability to resolve problems quickly. For imported printed-electronics solutions, the challenge is often less about product differentiation than about who owns the failure if the deployment does not perform.
Local partnerships can address this, but only when roles are clearly defined. A distributor that can import goods may not be able to support systems integration. A systems integrator may understand the customer environment but lack materials expertise. A packaging converter may provide production scale but have no process controls for conductive inks or electronic testing. The strongest route often combines application knowledge, local commercial coverage, and specialist manufacturing competence.
Saudi procurement can also involve local-content expectations, particularly in major projects and institutional purchasing. The exact relevance varies by buyer, sector, and tender. It should not be treated as a universal requirement, but suppliers should expect questions about domestic value creation, local assembly, training, maintenance capacity, spare-part availability, and technology transfer. A credible localisation plan can matter more than a vague commitment to open a future office.
Compliance cannot be handled at the shipment stage
Importing an electronic or connected product into Saudi Arabia may involve more than customs documentation. Product conformity obligations can apply through the Saudi Standards, Metrology and Quality Organization (SASO) framework and the Saber platform, depending on the product classification. Wireless or telecommunications functions may bring additional requirements under the Communications, Space and Technology Commission (CST) regime. Products with batteries, chargers, radio modules, consumer-facing electrical functions, or data connectivity should be assessed as complete systems rather than as isolated printed components.
For suppliers, the practical lesson is straightforward: compliance responsibility should be assigned before commercial quotations are finalised. Determine the importer of record, product classification, applicable technical regulations, test reports required, label and Arabic-language information needs, and whether the local partner is authorised to handle the relevant filings. A printed NFC label attached to consumer packaging may have a different pathway from a connected sensor transmitting data through a wireless module.
Data protection is another consideration for solutions that collect identifiable customer, employee, patient, or location information. Saudi Arabia’s Personal Data Protection Law creates a higher level of scrutiny around data collection and processing practices. The risk is not limited to cloud software providers. A sensor, wearable, smart shelf, or tracking tag can become part of a regulated data chain when it is linked to individuals or identifiable behaviour.
The economics of printing are often misunderstood
Printed electronics is frequently presented as a route to lower cost because additive processes can use less material and support high-volume production. That can be true at scale. It is not automatically true for market entry.
Early deployments may require customised substrates, antenna designs, ink formulations, protective coatings, reader infrastructure, software integration, and test procedures. Minimum order quantities for specialist materials can be high. Freight, local warehousing, import documentation, and replacement stock add cost. If the application requires frequent design changes, the savings from printing can be absorbed by qualification and rework.
Commercial evaluation should therefore focus on total deployment economics. Relevant questions include:
- What manual process, loss rate, energy use, or compliance exposure does the solution reduce?
- What percentage of units must perform correctly for the buyer to achieve value?
- Who pays for reader infrastructure, software integration, installation, and operator training?
- What happens when a printed component fails in the field: replacement, repair, or process fallback?
- Can the technology move from a paid pilot to repeat purchasing without redesign?
A pilot that proves technical function but does not establish these economics is an expensive demonstration, not market validation.
Entry risks that deserve more attention
The first risk is confusing project announcements with addressable demand. Saudi Arabia has many ambitious development programmes, but a technology supplier needs visibility into procurement timing, approved specifications, contractor selection, and operational ownership. Not every announced project turns into an immediate purchasing opportunity for specialised components.
The second is overestimating the willingness to pay for novelty. Buyers may be interested in flexible, thin, sustainable, or connected features, but budgets are typically released for measurable outcomes: lower shrinkage, better compliance, reduced energy use, faster processing, improved safety, or stronger customer retention. The technology must be attached to one of those outcomes.
The third is treating local representation as a formality. In complex deployments, local partners influence access to decision-makers, tender interpretation, Arabic documentation, installation quality, service response, and payment collection. A poorly aligned partner can delay market entry more than the absence of a partner.
The fourth is underestimating qualification time. Printed electronics can sit at the intersection of packaging, electronics, materials science, software, and regulated end-use sectors. Each stakeholder may require separate approval. A packaging team may accept the format while IT rejects the data architecture; an engineering team may approve performance while procurement challenges the warranty model.
A realistic outlook: selective scaling before broad adoption
The Saudi Arabia printed electronics market is unlikely to develop in a uniform way. High-volume consumer-device manufacturing will remain difficult to enter without deep supply-chain integration and substantial production capability. By contrast, targeted applications in smart packaging, logistics, industrial identification, retail operations, building systems, and specialist monitoring have a clearer path because they can be sold against a specific operational problem.
Over the next several years, the most credible suppliers will be those that reduce the gap between technology demonstration and operating proof. They will bring climate-tested designs, identify the relevant compliance route early, work with partners that can support the whole deployment, and structure pilots around measurable commercial outcomes. They will also resist the temptation to position every printed component as a smart-city or consumer-electronics solution.
For market entrants, the central judgement is not whether Saudi Arabia is ready for printed electronics in the abstract. It is whether a defined application can survive the country’s environmental conditions, fit its procurement reality, meet its regulatory obligations, and generate a return that remains visible after the pilot team has left the room.
Featured Reports Desk
Related News
- 00
0000-00
What makes a market analysis reports portal reliable for strategic planning? - 00
0000-00
What an industry insights report can reveal about market demand shifts - 00
0000-00
How to Assess the Future Credibility of Market Research Before Using It - 00
0000-00
Saudi Arabia’s Printed Electronics Market: Demand Drivers and Entry Risks - 00
0000-00
What Should Businesses Do When Market Reports Contradict Each Other?
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.