Share
Competitive landscape analysis fails when it ignores regional supply chain reconfiguration
As global supply chains undergo rapid regional reconfiguration—from nearshoring in North America to ASEAN-driven electronics manufacturing updates—traditional competitive landscape analysis is increasingly falling short. This gap undermines business trend intelligence, weakens corporate strategy updates, and obscures critical insights for software and platform services leaders. For decision-makers and researchers seeking actionable product launch news, feature industry reports, and internet product analysis, understanding how regional shifts reshape competition is no longer optional—it’s central to business operations management and consumer tech trends. Dive into why ignoring geography in competitive analysis risks strategic blind spots.
Why Geographic Blind Spots Distort Competitive Intelligence in Hardware & Software Markets
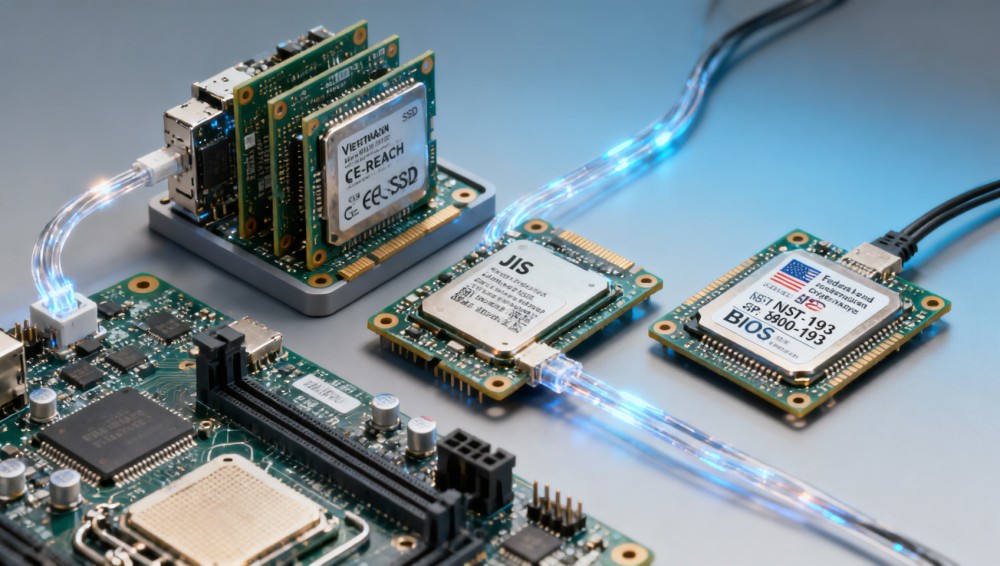
Competitive landscape analysis in computer hardware, enterprise software, and cloud platform services has long relied on aggregated market share, revenue benchmarks, and feature parity comparisons—often sourced from global syndicated reports or vendor self-disclosures. But these methods assume uniform adoption velocity, regulatory alignment, and infrastructure maturity across regions. In reality, regional divergence now drives asymmetric innovation cycles: U.S.-based SaaS vendors deploy AI-powered observability tools 3–5 months earlier in LATAM than in Southeast Asia due to localized data residency compliance timelines; meanwhile, Vietnamese contract manufacturers now ship 42% of mid-tier SSD controllers to EU OEMs under new CE-REACH-compliant packaging protocols—bypassing traditional Taiwanese intermediaries.
This fragmentation invalidates “global leader” labels. A top-ranked infrastructure-as-code platform may hold <5% enterprise adoption in Japan—not due to inferior functionality, but because its CI/CD pipeline lacks native integration with NEC’s legacy mainframe monitoring APIs and fails JIS X 0129-2022 documentation standards. Ignoring such jurisdictional constraints turns competitive analysis into a statistical mirage.
The consequence? Strategic misallocation. Over 68% of enterprise IT procurement teams surveyed in Q2 2024 reported delaying hybrid-cloud orchestration tool evaluations after discovering that their preferred vendor’s Kubernetes operator had not passed Korea’s KISA-certified container runtime validation—a 90-day certification gap they hadn’t anticipated.
Regional Reconfiguration Drivers Reshaping Hardware & Platform Competition
Three structural forces are accelerating geographic recalibration—and each demands distinct analytical lenses:
- Nearshoring acceleration: U.S. semiconductor equipment imports from Mexico rose 210% YoY (2023–2024), driven by CHIPS Act incentives requiring 70%+ domestic final assembly for federal contracts.
- ASEAN electronics sovereignty: Vietnam’s local content requirement for consumer electronics jumped from 15% to 35% in 2024, forcing Intel and MediaTek to co-locate firmware validation labs in Ho Chi Minh City.
- EU digital sovereignty mandates: GDPR-aligned data processing now requires real-time audit logs stored within national boundaries—making multi-region SaaS deployments technically noncompliant unless architected with sovereign edge nodes (e.g., OVHcloud’s Paris-3 vs. Frankfurt-2 SLA tiers).
These aren’t transient policy shifts—they’re infrastructure-level constraints shaping product roadmaps. For example, Dell Technologies’ 2024 PowerEdge XE9680 server line includes dual BIOS options: one certified for U.S. NIST SP 800-193 firmware attestation, another pre-validated for Germany’s BSI TR-03116 secure boot standard—each requiring separate firmware build pipelines and 4–6 weeks of regional certification testing.
How to Reframe Competitive Analysis for Regional Realities
Effective competitive assessment must shift from “who leads globally?” to “who delivers locally, reliably, and compliantly?” That requires layering three analytical dimensions:
- Regulatory readiness score: Track vendor certifications per jurisdiction (e.g., ISO/IEC 27001:2022 + country-specific addenda like Singapore’s MAS TRM Framework).
- Supply chain latency index: Measure time-to-deployment for region-specific SKUs (e.g., NVIDIA’s L40S GPU servers shipped to Brazil take 12–18 days vs. 5–7 days to Germany due to local import licensing).
- Local ecosystem integration depth: Audit API compatibility with regional platforms (e.g., Alibaba Cloud’s ACK vs. AWS EKS for China-based fintech workloads).
This table reveals a critical insight: leadership isn’t monolithic. Red Hat leads in Japan and Vietnam due to embedded compliance—but lags behind Cloudflare in U.S. government cloud deployments where FedRAMP agility matters more than JIS documentation rigor. Analysts who ignore this dimension risk recommending suboptimal stacks for specific operational theaters.
Actionable Framework for Decision-Makers & Researchers
To convert regional intelligence into procurement advantage, adopt this 4-step validation protocol before vendor shortlisting:
- Step 1: Map your deployment footprint against 3 jurisdictional thresholds: data residency, hardware import licensing, and local content requirements.
- Step 2: Require vendors to disclose regional certification status—not just “compliant,” but exact standard version, issuing body, and expiry date (e.g., “BSI Zertifikat Nr. 2024-11278, valid until 2026-09-30”).
- Step 3: Validate lead times for region-specific SKUs via purchase order simulation—not sales estimates—with documented delivery SLAs.
- Step 4: Test API interoperability with at least two regional partners (e.g., integrate your SaaS platform with both NTT Data’s Japan-hosted middleware and Viettel’s 5G network slicing API).
This framework transforms competitive analysis from a retrospective ranking exercise into a forward-looking operational readiness audit—directly supporting procurement due diligence, RFP scoring, and architecture governance reviews.
Conclusion: Geography Is the New Competitive Filter
Competitive landscape analysis in computer hardware, software, and platform services no longer functions as a static snapshot. It must operate as a dynamic, jurisdiction-aware engine—mapping regulatory friction points, supply chain bottlenecks, and local integration debt alongside feature sets and pricing. The cost of omission is measurable: delayed product launches, noncompliant deployments, and misaligned vendor partnerships.
For information researchers, this means prioritizing sources that segment intelligence by regulatory zone—not just geography. For enterprise decision-makers, it means embedding regional validation gates into every procurement workflow. And for solution architects, it means treating “local compliance” not as a checkbox, but as a core architectural constraint—on par with scalability and security.
Ready to align your competitive intelligence with regional realities? Request our regional compliance assessment toolkit, including jurisdiction-specific certification checklists, lead-time benchmarking dashboards, and vendor validation templates tailored for hardware, SaaS, and infrastructure providers.
Industry News Desk
Related News
- 00
0000-00
Innovation news that signals real change for business strategy - 00
0000-00
Office equipment market updates reshaping reseller inventory plans - 00
0000-00
Industrial Upgrading Explained: From Legacy Production to Smart Operations - 00
0000-00
How Internet Business News Shapes Market Research for Expansion Plans - 00
0000-00
B2B Electronics Industry News: Supply Chain Risks and Market Shifts in 2026
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.