Share
Resolving Conflicts Between Internal Data and Industry Forecasts for Market Entry
Resolving Conflicts Between Internal Data and Industry Forecasts for Market Entry
When internal sales signals point one way and industry forecasts point another, market entry decisions can quickly become high-stakes. For consumer electronics leaders asking, “how do i validate market entry decisions when internal data contradicts industry forecasts?”, the answer is rarely to choose one dataset and dismiss the other. It is to understand what each source actually measures, test the assumptions underneath it, and distinguish a temporary demand pattern from a durable market shift.
This conflict is common in categories such as smart home devices, personal audio, small appliances, displays, home security products, and connected accessories. A manufacturer may see rising inquiries from distributors in a target country while an external forecast predicts slowing category growth. Or internal e-commerce conversion may look weak even as market researchers describe strong household adoption. Both signals can be accurate. They may simply refer to different price tiers, retail channels, buyer groups, or points in the purchase cycle.
A sound market entry decision does not require perfect certainty. It requires an evidence trail strong enough to justify an initial commitment, define what must be learned next, and limit the cost of being wrong.
Start by Asking Why the Evidence Conflicts
Internal data is often closer to current commercial activity, but it can be narrow. It may reflect existing customers, a limited range of SKUs, a promotional period, or the capabilities of one distribution partner. Industry forecasts offer a wider view, yet they are usually built from category definitions and historical assumptions that may not match a company’s product positioning.
Before debating which source is “right,” identify the unit of comparison. A forecast for the overall smart speaker market may include entry-level voice devices, while a company’s internal demand signal comes from premium multi-room audio systems. A forecast for television sales may be based on unit volumes, whereas internal planning is focused on revenue from larger-screen models or value-added installation services. Those are related markets, not identical markets.
Timing matters as well. Internal data can capture a short-lived stockout at a competitor, a retailer campaign, or pent-up replacement demand. Forecasts can lag fast changes in channel inventory, currency movements, component availability, or consumer confidence. Neither source should be treated as a stable fact until its collection period, methodology, and coverage are clear.
A useful first exercise is to document each claim in plain language: what market is growing or shrinking, for whom, through which channel, at what price point, and over what period? Many apparent contradictions disappear at this stage.
Audit Internal Signals Before Treating Them as Demand
Internal numbers can feel more trustworthy because they come from the business itself. Yet sales dashboards often combine several different signals: shipments, sell-in orders, website leads, distributor forecasts, search demand, retail sell-through, returns, and customer support activity. They should not carry the same weight.
For market entry, sell-through data is generally more revealing than sell-in data, provided it is available and reasonably current. A distributor’s initial order may reflect a launch commitment or inventory build rather than confirmed end-user demand. High product-page traffic may signal curiosity, but it does not prove that a price point, warranty policy, or delivery promise is acceptable in the target market.
Look for evidence that moves beyond intent. In consumer electronics, that could include repeat purchases of compatible accessories, low cancellation rates after delivery estimates are shown, requests for local plug configurations, inquiries about language support, or retailer feedback on the features customers compare before purchase. Returns and support tickets are equally valuable. They often expose a mismatch between a product’s apparent appeal and its practical fit in local homes.
Data should also be segmented rather than averaged. An attractive conversion rate among existing brand owners may say little about unfamiliar buyers. Demand in major cities may not transfer to secondary regions where installation support, broadband reliability, retail access, or household size differs. Internal performance in one neighboring country is useful context, not automatic proof that the next market will respond in the same way.
Interrogate Forecasts as Decision Inputs, Not Verdicts
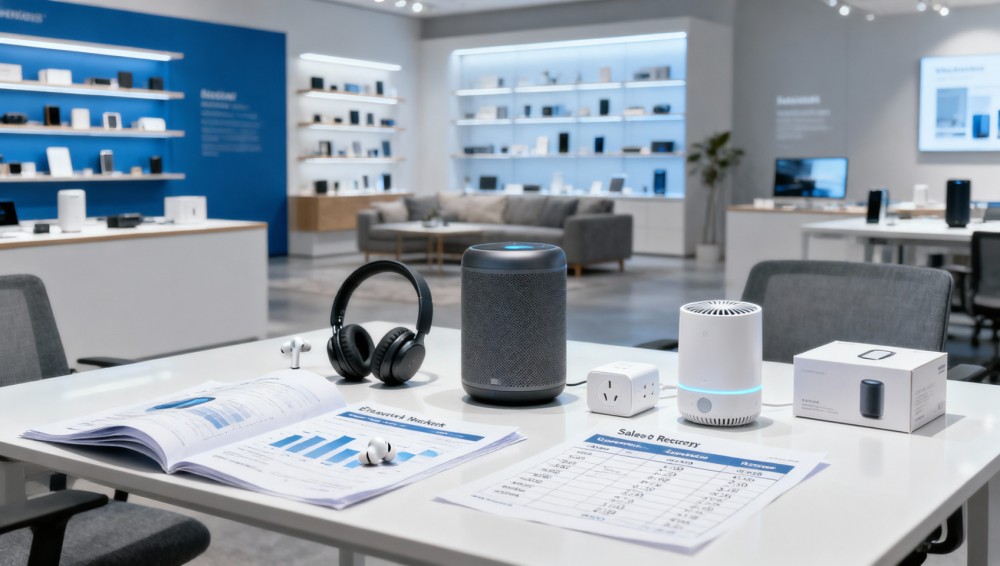
Industry forecasts are valuable when they clarify the broader forces shaping a category: household replacement cycles, channel consolidation, price pressure, component trends, consumer preferences, and technology transitions. The problem begins when a headline growth rate is treated as a direct instruction to enter or avoid a market.
Review the forecast’s category scope and assumptions. Does it measure retail value, factory shipments, installed base, or unit demand? Does it include refurbished products? Does it group connected home products with conventional appliances? Does it assume a certain rate of inflation, a particular consumer spending outlook, or continued availability of a key technology? A forecast may be well constructed and still not answer the commercial question in front of the company.
It is also worth comparing more than one external source where practical. The goal is not to average every number into a false sense of precision. Instead, look for areas of agreement and the reasons for disagreement. If several sources see pressure in entry-level tablets but point to resilience in education, remote work, or premium productivity devices, a company should assess whether its offer fits one of those segments rather than relying on the category average.
External research becomes more useful when it is paired with ongoing reporting on industry news, market updates, trend analysis, company developments, product insights, and feature reports. For decision-makers working across internet, business services, consulting, office supplies, and consumer electronics, this broader view can reveal signals that a static forecast misses: a retailer changing its assortment, a platform updating device requirements, or a competitor shifting from direct sales to local distribution.
Build a Reconciliation Matrix Around the Real Entry Question
The practical question is usually not, “Will this whole market grow?” It is closer to: “Can we profitably establish a credible position with this product range, through this route to market, within an acceptable level of operational risk?” That question needs a narrower framework.
This matrix prevents a common error: using a single positive indicator to compensate for an unrelated weakness. Strong interest does not resolve a certification gap. A favorable market forecast does not fix an unworkable service model. The evidence needs to support the same decision, not merely create a persuasive-looking stack of charts.
Test the Disagreement With a Controlled Market Experiment
When the stakes permit, the best response to conflicting information is often a staged entry rather than a full launch or a complete retreat. A controlled pilot can test the exact assumptions that forecasts and internal data cannot settle.
The pilot should be designed around a learning objective, not merely a sales target. For example, a company may need to learn whether consumers will accept a mid-premium price after local taxes and channel margin are included; whether a smart device can be installed without costly support; or whether retailer staff can explain the main product distinction clearly enough to sustain conversion. Limit the initial SKU range, choose channels deliberately, and avoid interpreting discount-driven volume as proof of normal demand.
Define decision thresholds before the launch. They might include a minimum level of sell-through after allowing for seasonality, an acceptable return pattern, a target rate of successful activation, or evidence that local support can resolve common issues within the planned cost structure. The exact threshold depends on product economics and risk tolerance, but the discipline matters more than the number itself.
A pilot should also include qualitative evidence. Interviews with retailers, installers, customer service teams, and early buyers often explain outcomes that raw sales data cannot. A low conversion rate may be caused by price, but it may also reflect unclear packaging, missing local-language instructions, an incompatible plug, insufficient app localization, or hesitation about warranty handling. Consumer electronics are ecosystems, not isolated objects.
Treat Compliance and Service as Market Evidence
Market potential is sometimes evaluated before operational feasibility. That sequence can create expensive delays. Depending on the product and destination, consumer electronics may need to meet requirements related to electrical safety, electromagnetic compatibility, radio equipment, energy labeling, batteries, product labeling, waste handling, data protection, or consumer warranties. The applicable rules must be confirmed for the specific product and local market; assumptions based on another country can be unreliable.
These requirements are not just a legal checklist. They affect launch timing, packaging, documentation, testing budgets, repair workflows, and distributor responsibilities. If compliance evidence is incomplete or local after-sales coverage is uncertain, a forecast of growing demand should not be enough to authorize a broad rollout.
Service capacity can be a differentiator in categories where setup, connectivity, replacement parts, or software updates influence customer satisfaction. Leaders should ask whether the local model can support the product after the point of sale, not only whether it can place units on shelves.
Make a Reversible Decision Where the Evidence Remains Uncertain
Not every contradiction will be resolved before a decision deadline. In that case, choose the least irreversible option that produces meaningful evidence. This may mean entering through a limited distributor agreement, prioritizing a small number of adaptable products, using a defined review period, or delaying commitments that require extensive dedicated inventory.
The strongest entry plans state what would change the decision. If conversion remains weak after packaging and pricing are validated, will the company pause? If a particular channel produces better-quality demand, will resources shift there? If external indicators worsen but pilot sell-through remains healthy, which signal will take priority and why? Writing these conditions in advance protects the team from defending the original narrative after new evidence appears.
For leaders confronting conflicting signals, the useful question is not whether internal data or industry forecasts deserve absolute trust. It is whether the available evidence supports a defined customer segment, a workable route to market, a compliant product, and an operating model that can absorb uncertainty. Validate those elements separately, test the gaps through a focused launch, and let real market behavior refine the forecast rather than forcing the business to conform to it.
Overseas Marketing Editorial Team
Related News
- 00
0000-00
How digital advertising trends are changing audience targeting - 00
0000-00
How to use purchase history for email marketing segmentation - 00
0000-00
Internet trends 2026 that could reshape how businesses reach customers - 00
0000-00
Can software manage multi-channel social ads without duplicate spend? - 00
0000-00
Resolving Conflicts Between Internal Data and Industry Forecasts for Market Entry
0000-00
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.