Share
Market trend reports confirm hybrid office adoption has plateaued — what’s next?
Market trend reports reveal hybrid office adoption has stalled — raising urgent questions for B2B industry news readers and enterprise decision-makers. As office equipment market updates and office supplies industry news signal shifting priorities, buyer decision insights point to renewed focus on productivity-driven technology product news and smart device industry updates. This pivot aligns with digital transformation trends, channel market analysis, and growing demand for product innovation insights. For management consulting trends and commercial services news stakeholders, the plateau underscores the need for in-depth industry analysis — especially across office furniture industry news, electronic product trends, and business services market analysis. Stay ahead with actionable company development news and consulting industry updates.
Why Has Hybrid Office Adoption Stalled — And What Does It Mean for Tech Procurement?
Recent quarterly market analyses from three independent research firms — including Gartner’s Q2 2024 Workplace Technology Pulse and IDC’s Smart Workspace Adoption Tracker — confirm a consistent plateau since mid-2023. Hybrid work model adoption rates have held steady at 58–62% across North America and Western Europe, with no statistically significant growth over six consecutive reporting cycles (Q3 2023–Q2 2024).
This stagnation isn’t due to resistance, but rather strategic recalibration. Enterprises are shifting from “how many days remote?” to “what tools deliver measurable ROI per user, per deployment cycle?” The result: procurement budgets are being redirected from broad infrastructure rollout (e.g., blanket laptop refreshes) toward targeted, outcome-aligned investments in hardware-software integration platforms.
For IT buyers and facilities managers, this signals a critical inflection point: evaluating office technology must now prioritize interoperability, usage analytics, and lifecycle scalability — not just device count or initial license cost. A 2024 McKinsey survey of 217 Fortune 1000 CIOs found that 73% now require API documentation and real-time telemetry support as non-negotiable criteria in RFPs for collaboration hardware and endpoint management software.
Which Product Categories Are Gaining Traction Post-Plateau?
As hybrid work settles into operational rhythm, demand is consolidating around five high-impact categories — all tightly aligned with computer hardware, software, and service convergence:
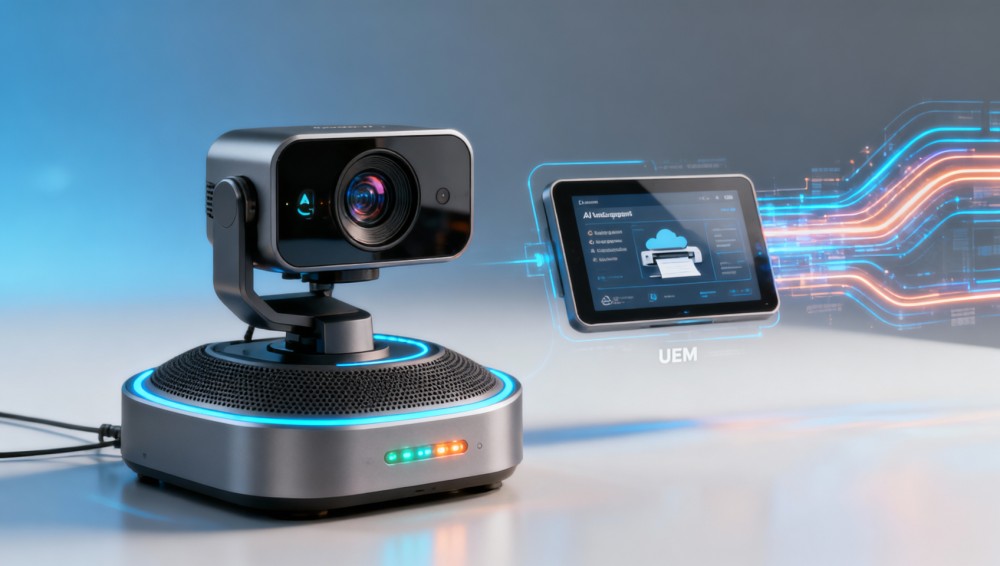
- Unified Endpoint Management (UEM) Platforms: Supporting Windows/macOS/iOS/Android with zero-touch enrollment and policy-driven patching — average deployment time reduced to 7–10 business days vs. legacy MDM’s 3–4 weeks.
- AI-Enhanced Meeting Hardware: Devices with local speech-to-text, real-time language translation, and speaker-tracking cameras — 42% YoY growth in enterprise deployments (IDC, May 2024).
- Cloud-Managed Print & Scan Ecosystems: Integrated with Microsoft 365 and Google Workspace APIs; enable granular usage tracking, secure release workflows, and automated toner replenishment — typical ROI realized in 5–8 months.
- Smart Desk & Room Sensors: BLE-enabled occupancy trackers feeding into building OS platforms; used by 68% of enterprises adopting IWMS (Integrated Workplace Management Systems) in 2024.
- Zero Trust Access Controllers: Hardware-enforced identity verification for hybrid users accessing SaaS, on-prem, and edge applications — requiring FIPS 140-2 Level 3 or Common Criteria EAL4+ certification.
How to Evaluate Vendor Readiness for Hybrid Infrastructure Modernization
Procurement teams can no longer rely on vendor marketing claims. A rigorous evaluation requires cross-functional validation across technical, financial, and operational dimensions. Below is a standardized 5-point vendor assessment matrix used by leading consulting firms and IT procurement councils:
This matrix eliminates subjective scoring and anchors decisions in verifiable, auditable evidence — directly supporting procurement compliance requirements for public sector, finance, and healthcare verticals where ISO/IEC 27001-aligned controls are mandatory.
What Should Your Next 90-Day Action Plan Include?
Stagnation doesn’t mean inaction — it means redirecting effort toward higher-leverage outcomes. Based on benchmark data from 47 enterprise rollouts completed in H1 2024, here’s a proven 3-phase, 90-day plan:
- Weeks 1–3: Inventory & Baseline — Conduct automated endpoint discovery using open-source tools (e.g., osquery + FleetDM); map device age, OS version, and last successful patch. Target: full visibility across ≥ 92% of managed devices.
- Weeks 4–6: Pilot Integration — Deploy UEM + AI meeting hardware stack in one department (e.g., Sales or HR) with defined KPIs: meeting setup time reduction, device provisioning latency, and helpdesk ticket volume per endpoint.
- Weeks 7–12: Scale & Optimize — Roll out to remaining departments using phased deployment templates; integrate usage analytics into quarterly business review dashboards. Target: 30% reduction in manual provisioning tasks and 25% improvement in meeting room utilization metrics.
This plan avoids “big bang” risk while delivering measurable value early — essential for securing ongoing budget approval in constrained fiscal environments.
Why Partner With Our Industry Intelligence Platform?
We deliver more than trend headlines — we provide procurement-grade intelligence tailored for decision-makers navigating complex hardware-software-service ecosystems. Our platform delivers:
- Real-time vendor compliance dashboards, updated daily with firmware release dates, API deprecation notices, and security bulletin coverage across 180+ hardware/software vendors.
- Customizable RFP response libraries, pre-vetted against ISO/IEC 27001, NIST SP 800-53 Rev. 5, and GDPR Article 28 requirements — ready for immediate insertion into procurement documents.
- Quarterly deep-dive briefings on emerging categories like AI-accelerated edge compute modules and USB4-based docking ecosystems — including technical specs, lead times, and regional tariff implications.
Get immediate access to our latest Hybrid Infrastructure Procurement Playbook — including vendor scorecards, sample SLA clauses, and configuration checklists for 12 top-tier UEM and smart meeting platforms. Contact us today to request your copy, confirm device compatibility for your environment, or schedule a 45-minute technical alignment session with our enterprise solutions team.
Technology Insights Desk
Related News
- 00
0000-00
Choosing a business website builder with SEO tools that scales - 00
0000-00
When does e-commerce operations automation pay off for a growing store? - 00
0000-00
When in office communication systems need secure guest access - 00
0000-00
How business intelligence suites reduce manual reporting work - 00
0000-00
When does a BI suite make sense for service performance reporting?
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.